
LSO Spot Audit: Ontario Law Firm Trust Accounting Compliance Guide
Ontario law firms must maintain accurate financial records, safeguard client trust funds, and comply with the Law Society of Ontario’s (LSO) requirements for trust accounting and client identification. Understanding LSO By-Law 9 and By-Law 7.1 is essential for maintaining appropriate financial controls and preparing for a Law Society spot audit.
The LSO identifies recurring audit deficiencies involving incomplete financial records, late monthly trust comparisons, unresolved reconciling items, electronic trust transfer documentation, client identification, and source-of-funds records. These findings demonstrate why law firms need consistent procedures, timely reviews, and reliable supporting documentation.
Written by Knowledge Team, posted on October 24, 2026
Whether you operate a sole practice, professional corporation, or multi-lawyer firm, understanding these requirements can help you identify gaps in your processes and strengthen your compliance practices.
This guide explains key LSO trust accounting requirements, common spot audit findings, and how legal practice management software can support your firm’s financial workflows.
Important: This article provides general information, not legal advice. Always consult the current consolidated LSO by-laws and applicable guidance to confirm the requirements for your practice.
Common LSO Spot Audit Findings
An LSO spot audit examines a firm’s compliance with applicable professional and financial record-keeping obligations. Depending on the circumstances, an auditor may request accounting records, supporting documentation, transaction details, and explanations of the firm’s procedures.
The LSO’s published spot audit guidance identifies several recurring compliance issues.
| Common audit finding | Recommended preventive control |
|---|---|
| Financial records are not current | Establish consistent posting procedures and review outstanding entries regularly. |
| Trust journal entries lack required particulars | Standardize transaction documentation and review supporting records. |
| Monthly trust comparisons are late | Assign responsibility for preparation, review, and sign-off deadlines. |
| Reconciling items remain unresolved | Investigate discrepancies, document their causes, and track corrective action. |
| Electronic trust transfer records are incomplete | Follow the applicable requisition, authorization, and confirmation procedures. |
| Client trust balances remain inactive | Review aged balances and document appropriate follow-up. |
| Client identification records are incomplete | Incorporate applicable identification and verification requirements into matter-opening workflows. |
| Source-of-funds documentation is missing | Establish procedures to obtain and retain information required in the circumstances. |
1. LSO By-Law 9: Financial Records and Retention Requirements
Ontario lawyers must maintain the financial books, records, and supporting documents required by By-Law 9. These records should be complete, current, organized, and available when required.
General account records
The LSO specifies a six-year retention period for certain general account records. Depending on the record category, these may include receipts and disbursements journals, fee books or billing records, and duplicate cash receipt records.
Trust account records
Certain trust account records are subject to a ten-year retention period. Relevant categories include trust receipts and disbursements journals, individual client trust ledgers, monthly trust reconciliations and comparisons, bank statements, detailed deposit documentation, and records supporting electronic trust transfers.
The applicable period and calculation must be confirmed against the current rules and the specific record category.
How to strengthen record retention
A documented retention policy should identify:
- Each category of financial and supporting record.
- The applicable retention period.
- Where the record is stored.
- Who is responsible for maintaining it.
- How authorized personnel can retrieve it when needed.
Electronic records should be organized, appropriately protected, and retrievable in a usable format. Firms should not assume that their financial institution will retain bank records for the full period required of the firm.
For a related discussion of document organization and digital workflows, see SharePoint Legal Document Management.
Official resource: LSO By-Law 9
2. Monthly Three-Way Trust Reconciliation: The 25th-Day Deadline
One of the most important recurring obligations under By-Law 9 is the monthly trust reconciliation and comparison.
Under section 18(8), the required monthly trust reconciliation, client trust listing, and comparison must be completed by the 25th day of the following month.
For example, the comparison for a month ending September 30 must be completed by October 25.
What is a three-way trust comparison?
A three-way comparison brings together three sets of financial information:
- Adjusted trust bank balance: The bank balance after accounting for appropriate outstanding reconciling items.
- Trust receipts and disbursements journal balance: The balance reflected in the firm’s trust accounting records.
- Total client trust ledger balances: The combined balances held on behalf of individual clients.
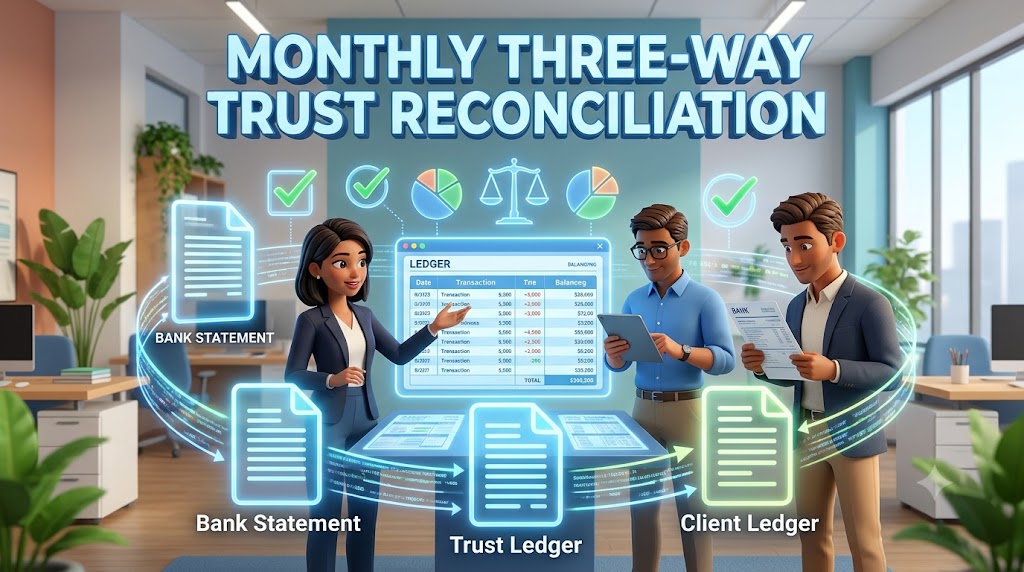
These figures should reconcile. A difference may indicate a missing transaction, posting error, incorrect client allocation, bank discrepancy, or another issue that requires investigation.
The monthly process should include:
- Preparing the trust bank reconciliation.
- Producing the client trust listing as of the relevant month-end.
- Comparing the adjusted bank balance with the trust journal and client trust ledger totals.
- Investigating and documenting discrepancies.
- Completing the required review and sign-off.
Firms should follow the applicable monthly requirements even when there has been little or no account activity.
How software can support monthly reconciliation
A structured workflow can help staff track deadlines, organize supporting records, and identify unresolved discrepancies. Accounting software may also help reduce manual calculations and improve visibility into outstanding review tasks.
However, automation does not replace the required reconciliation, investigation, or professional review.
For more details, read Reconciliation for Lawyers: Trust Accounts and Three-Way Compliance.
3. Trust Journal Entries: Required Transaction Particulars
Section 18 of By-Law 9 specifies requirements for trust accounting records, including particulars that must be recorded for applicable transactions.
Incomplete transaction descriptions can make it difficult to determine why money was received or paid, for whom the transaction was conducted, and whether it was properly supported.
For trust payments, firms should ensure that the records contain the particulars required by the applicable provision, including relevant information about:
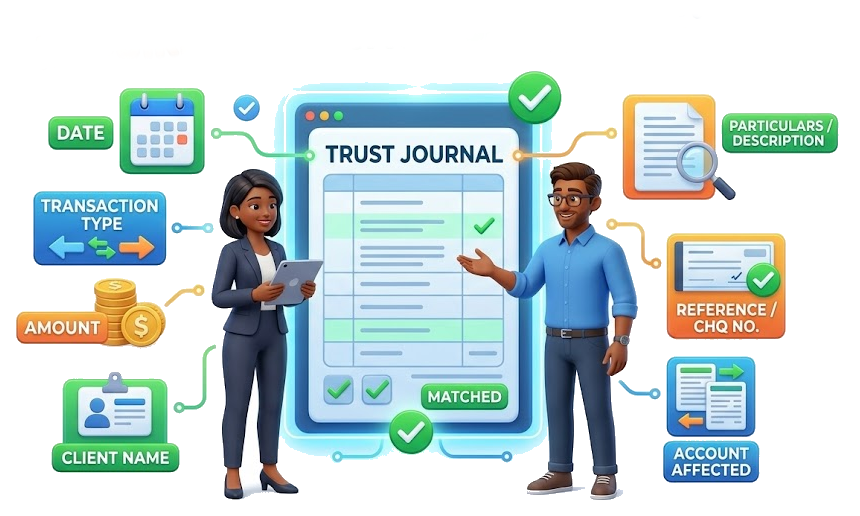
- The date of payment.
- The amount paid.
- The payee.
- The method of payment and applicable transaction or requisition references.
- The purpose of the payment.
- The client on whose behalf the payment was made.
The exact requirements depend on the transaction and the applicable rule. Each entry should be sufficiently clear to support review and traceability.
Recommended trust accounting controls
Establish a consistent process that links each payment to the appropriate client matter and supporting authorization.
Before finalizing a transaction, staff should check for missing information, incorrect amounts, and incomplete documentation. Corrections should be recorded in accordance with the firm’s procedures and applicable requirements.
When selecting legal accounting software for law firms, evaluate whether the system supports matter-linked accounting, appropriate transaction records, reporting, and review workflows.
4. Trust Deposits, Deposit Slips, and Source-of-Funds Documentation
Trust deposit records should provide appropriate supporting evidence for the receipt of client funds. The firm’s procedures should preserve the documentation required under By-Law 9 and address any applicable source-of-funds obligations under By-Law 7.1.
A sound deposit workflow should help staff identify and document:
- The date and amount of the deposit.
- The client or matter associated with the funds.
- The source of the funds, where required.
- The relevant bank deposit documentation.
- Any additional supporting records required for the transaction.
Retain detailed duplicate deposit slips and other supporting records as required by the applicable rules.
When a deposit is made through an automated teller machine or another electronic channel, follow the applicable LSO requirements and retain the documentation needed to support the transaction. Do not assume that a bank receipt alone satisfies every record-keeping or source-of-funds obligation.
How to improve deposit documentation
Create a standard procedure for linking deposits to client matters, recording required information, and resolving missing documentation promptly.
Where appropriate, incorporate deposit documentation into the firm’s digital matter-management workflow so that authorized staff can locate supporting records when needed.
5. Electronic Trust Transfers and Form 9A
Electronic trust transfers require careful documentation and compliance with the applicable requirements of By-Law 9.
Form 9A and the associated bank confirmation records form part of the documentation for electronic trust transfers. Incomplete authorizations, missing transaction particulars, or inadequate supporting records can create problems during an LSO spot audit.
Build a documented electronic transfer workflow
Step 1: Prepare the requisition. Complete the applicable Form 9A fields and include the required transaction, client, payee, and banking information.
Step 2: Obtain the required authorization. Ensure the requisition is approved and signed in accordance with the current By-Law 9 requirements before proceeding with the transfer.
Step 3: Execute and document the transfer. Follow the applicable procedures for carrying out the transaction and recording it in the firm’s trust accounting records.
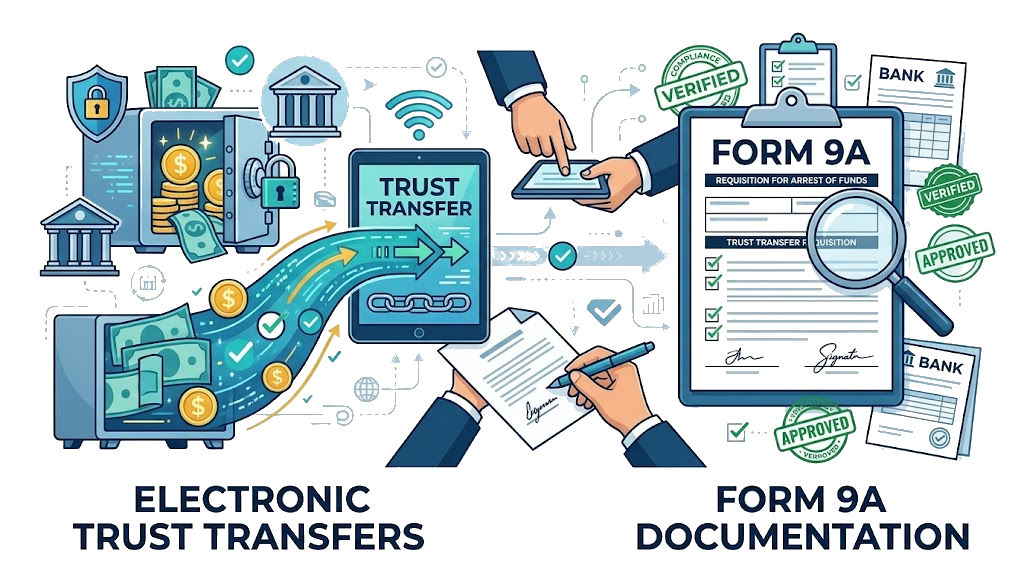
Step 4: Verify the bank confirmation. Check the bank’s confirmation against the requisition and transaction details, completing any required annotations, signatures, and dating.
Step 5: Retain supporting documents. Preserve the requisition, bank related accounting records for the applicable retention period.
The required timing, authorization, signature, and confirmation procedures should be verified against the current regulation and Form 9A instructions. Firms should not rely on a generic workflow if the applicable rules prescribe a specific procedure.
Where software can help
A legal accounting system can help organize transfer records, associate transactions with the correct matters, and make supporting documentation easier to locate. PageLightPrime can automate Form 9 compliance for Ontario law firms.
Official resource: LSO By-Law 9
6. Client Identification and Verification Under By-Law 7.1
Client identification and verification are distinct obligations under Part III of By-Law 7.1. Understanding the difference is important when designing matter-opening procedures and documenting transactions involving funds.
The applicable requirements depend on the circumstances of the retainer, the activities performed, and any relevant exemptions.
Client identification
Section 22 addresses when licensees must comply with the client identification requirements in section 23.
Depending on the client and circumstances, required information may include:
- For an individual, identifying information such as their name, address, telephone number, and occupation.
- For an organization, identifying information about the organization and individuals authorized to provide instructions, as required by the applicable provisions.
Firms should establish procedures to collect the required information and retain appropriate records.
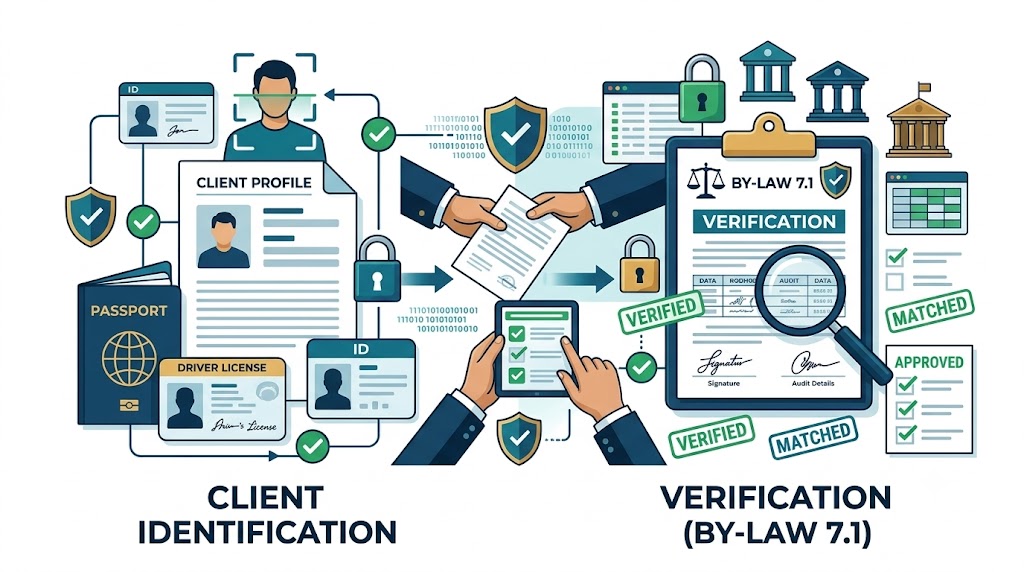
Client verification and source of funds
Client verification is a separate obligation from collecting identifying information. By-Law 7.1 addresses verification in specified circumstances involving the receipt, payment, or transfer of funds, subject to applicable exemptions.
The rules also address inquiries about the source of funds. Firms should establish procedures for obtaining and documenting the information required in the circumstances of each transaction.
A matter-opening checklist can help staff identify which requirements apply. A separate transaction workflow can prompt additional steps when funds are received, paid, or transferred.
Important: Identification, verification, and source-of-funds requirements are not interchangeable. Do not assume that the same requirements apply without exception to every retainer.
Official resource: LSO By-Law 7.1
7. Trust Account Designations and Reconciliation Discrepancies
By-Law 9 establishes requirements for the designation of trust accounts. Section 7 addresses how a licensee’s trust account must be designated, including the relationship between the account name and the licensee or firm.
Firms should verify that their account designations comply with the applicable requirements and accurately reflect their legal and professional structure.
Investigate reconciliation discrepancies promptly
A discrepancy between the trust bank balance, accounting journal, and client trust ledger totals should not be ignored or carried forward without investigation.
Potential causes include:
- Transactions recorded in the wrong period.
- Missing or duplicated entries.
- Incorrect amounts or client allocations.
- Outstanding cheques or deposits.
- Bank errors or other unreconciled transactions.
These are possible explanations, not a substitute for investigating the specific discrepancy.
Document the cause, corrective action, and resolution. If an error affects client trust funds, take appropriate steps under the applicable professional obligations and seek qualified guidance when necessary.
Recommended internal controls
Assign responsibility for each outstanding reconciliation item, document its status, and review unresolved issues regularly until they have been addressed.
A clear record of the investigation and corrective action can also help the firm explain its financial records during an audit.
8. Funded Client Ledgers, Trust Shortages, and Inactive Balances
Trust funds must be handled in accordance with By-Law 9 and the lawyer’s obligations to clients. Firms should maintain controls to help prevent withdrawals that exceed the funds properly available for the relevant client or matter.
Monitor client trust ledger balances
Before making a trust disbursement, verify the available funds, client or matter allocation, authorization, and purpose of the payment.
A trust shortage or negative client ledger balance requires prompt investigation. Identify the cause and take corrective action consistent with the applicable rules and professional obligations. Do not treat an unexplained shortage as an ordinary reconciling item.
Review inactive trust balances
Section 8.1 of By-Law 9 addresses money retained in trust beyond a minimally reasonable period after the relevant legal services have been performed.
Firms should periodically review aged balances, determine whether funds remain properly payable, document client communications, and follow the applicable procedures before transferring or otherwise disposing of funds.
Where a client cannot be located, the firm should consult the applicable requirements and LSO guidance to determine whether the Law Society’s Unclaimed Trust Fund process applies.
Practical compliance tip: Maintain a report of aged trust balances, assign responsibility for follow-up, and document the steps taken to resolve each outstanding matter.
Official resource: LSO By-Law 9
9. Authorized Trust Withdrawals and Banking Controls
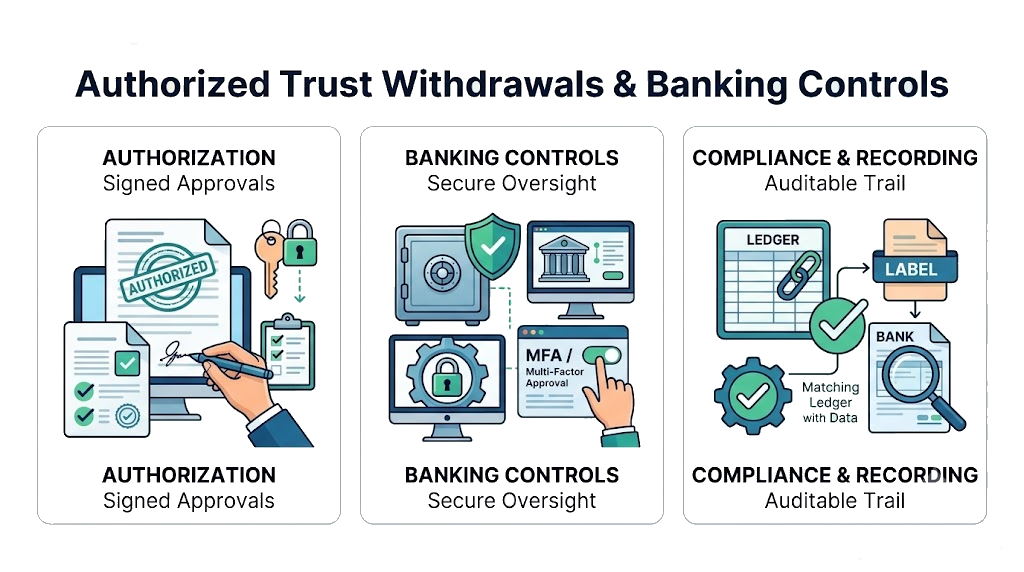
Trust withdrawals should be supported by the authorization, documentation, and accounting entries required under the applicable rules.
A firm’s internal controls should define who can authorize payments, who can prepare them, and how supporting documents are reviewed. Firms should also maintain appropriate continuity procedures for absences without bypassing required authorization.
Banking access should be restricted to authorized individuals. Review access privileges periodically and promptly address changes in staffing or responsibility.
For trust account payment methods, debit card use, and ATM transactions, follow the current By-Law 9 requirements and applicable banking arrangements. Avoid relying on informal assumptions about which methods are permitted.
Recommended banking safeguards
- Document trust payment and approval procedures.
- Review banking permissions periodically.
- Maintain appropriate backup arrangements for authorized personnel.
- Preserve supporting payment records.
- Review unusual transactions and exceptions promptly.
These safeguards can help reduce operational risk, but they do not replace the specific obligations established by the LSO.
10. Bill Before Transferring Earned Fees from Trust
Transferring client trust money to a general account requires compliance with the applicable rules governing trust withdrawals and payment of fees.
Where trust money is to be applied to fees, firms should ensure that the required bill has been prepared, delivered to the client, and recorded in accordance with the applicable requirements before making the transfer.
A proper billing record should clearly explain the legal services and disbursements being charged, as applicable. The amount transferred must be supported by the relevant entitlement and documentation.
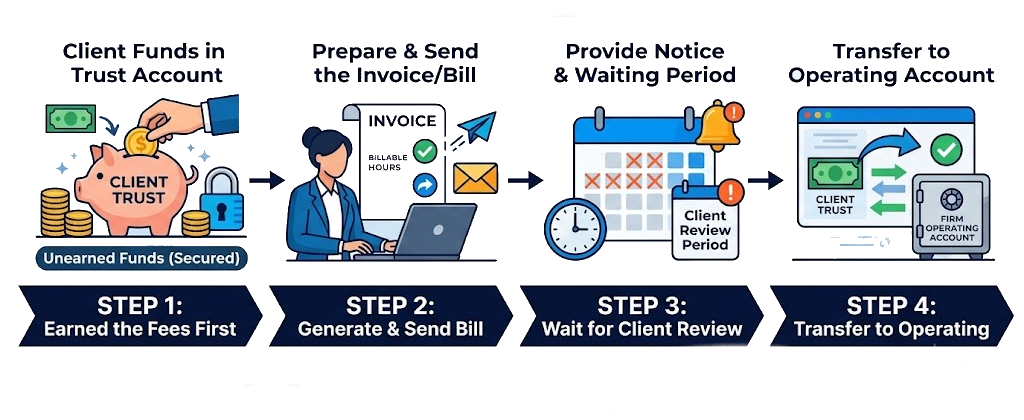
Establish consistent billing and transfer workflow
- Prepare the bill with sufficient detail to explain the fees and disbursements.
- Deliver the bill to the client as required.
- Record the billing and related accounting entries.
- Confirm that the amount to be transferred is properly supported.
- Complete and retain the required trust transfer documentation.
A clear process helps prevent premature transfers, incorrect client balances, and incomplete records.
For related capabilities, see PageLightPrime Legal Billing Software.
Official resource: LSO By-Law 9
LSO Trust Accounting Compliance Checklist for Ontario Law Firms
Use this checklist as a starting point for an internal review. It is not an exhaustive statement of every regulatory obligation.
- Financial records are current and complete.
- General and trust account records are retained for the applicable periods.
- Monthly trust reconciliation, client trust listing, and comparison are completed by the required deadline.
- The adjusted trust bank balance, trust journal balance, and total client trust ledger balances are compared.
- Required review and sign-off procedures are followed.
- Trust journal entries contain the required transaction particulars.
- Deposit slips and other supporting documents are retained as required.
- Form 9A requisitions and electronic transfer confirmations meet applicable requirements.
- Client identification, verification, and source-of-funds procedures reflect By-Law 7.1.
- Reconciliation discrepancies are investigated, documented, and corrected promptly.
- Aged client trust balances are reviewed and handled in accordance with applicable rules.
- Trust withdrawals and fee transfers are properly authorized and documented.
- Staff understand their responsibilities for trust accounting, approvals, and record retention.
Review this checklist against the current by-laws and the specific transactions and services your firm handles.
How Legal Practice Management Software Can Support LSO Compliance
Maintaining current financial records, completing monthly comparisons, documenting electronic trust transfers, and coordinating review responsibilities can create a substantial administrative burden for Ontario law firms.
Legal practice management software can support these workflows by linking accounting activity to client matters, organizing supporting documents, standardizing transaction processes, and improving visibility into outstanding tasks.
When evaluating a system, consider whether it supports:
- Matter-linked trust accounting records.
- Monthly reconciliation and comparison workflows.
- Reminders for recurring compliance deadlines.
- Documented approval and electronic transfer processes.
- Exception reporting and discrepancy tracking.
- Searchable financial records and supporting documentation.
- Appropriate access controls and audit history.
Software should be evaluated against the firm’s actual requirements. Automation can reduce manual work and help identify potential issues, but it does not replace professional oversight or guarantee compliance with the LSO’s rules.
Support Your Firm’s Trust Accounting Workflows with PageLightPrime
Ontario law firms need more than general accounting software to manage client funds responsibly. They need reliable matter-level financial records, clear trust-account balances, reconciliation workflows, and reporting that helps them prepare for reviews and audits under the Law Society of Ontario’s requirements.
PageLightPrime provides legal accounting and practice management capabilities for Canadian law firms, bringing financial workflows together with matter management, billing, legal document management , and day-to-day legal operations.
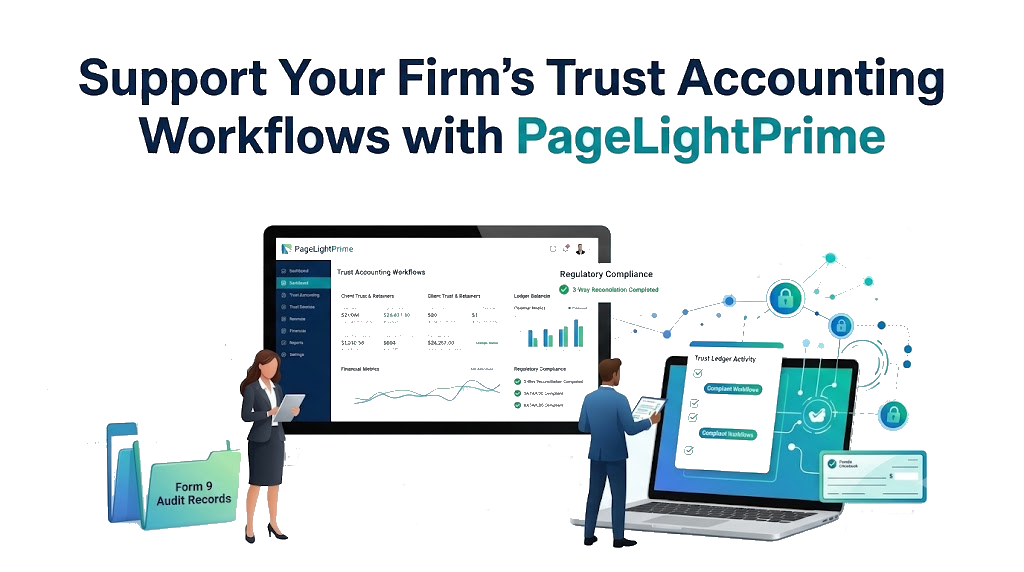
For firms looking to modernize their accounting processes, relevant capabilities include:
- Matter-based financial tracking: Connect financial activity to client matters to help maintain organized records of receipts, disbursements, fees, and balances.
- Trust accounting and reconciliation workflows: Use dedicated legal accounting capabilities to help organize client trust transactions, compare balances, and support reconciliation procedures.
- Integrated billing and accounting: Connect timekeeping, expenses, invoicing, and financial records to reduce duplicate data entry and disconnected workflows.
- Canadian tax and accounting support: Support Canadian law-firm financial operations, including applicable GST/HST and provincial tax workflows, depending on your firm’s needs and configuration.
- Microsoft 365 integration: Connect legal work with familiar tools and document workflows through the Microsoft ecosystem, helping firms manage information and collaborate more efficiently.
- Reporting and financial visibility: Use centralized financial information and reporting tools to help identify discrepancies, review transactions, and prepare for internal checks.
Official LSO Resources
For the most authoritative and current requirements, consult these resources:
Related Resources for Ontario Law Firms
Continue exploring trust accounting, financial controls, and legal practice management:
- Reconciliation for Lawyers: Trust Accounts and Three-Way Compliance — Understand trust reconciliation workflows and financial controls.
- Legal Accounting Software for Law Firms — Explore accounting, trust management, billing, and financial reporting capabilities.
- Legal Billing Software — Learn about legal invoicing, time tracking, and expense management.
- Legal Practice Management Software — Explore tools for managing client matters, documents, billing, and workflows.
- SharePoint Legal Document Management — Learn about digital document management for legal teams.
- Microsoft 365 Law Firm Software — Explore PageLightPrime’s Microsoft 365 approach to legal workflows.
“
Can PageLightPrime Help Ontario Firms With By-Law 9 Compliance?
Legal accounting software can help organize records and support consistent financial procedures, but technology alone does not establish compliance. Ontario firms must ensure their accounting practices, records, reconciliations, transfers, and reporting meet the applicable Law Society of Ontario requirements.
Before adopting any platform, confirm that its specific workflows support your firm’s obligations under By-Law 9, including the applicable recordkeeping and monthly reconciliation requirements. Your firm should also verify the software’s handling of required reports and documentation with its accounting team or a qualified legal accounting professional.
PageLightPrime can be part of a broader approach to improving financial organization and trust-accounting workflows. The firm remains responsible for reviewing its procedures, maintaining accurate records, and meeting its regulatory obligations.
“
Frequently Asked Questions (FAQ)
When is the monthly trust comparison due?
Under section 18(8) of By-Law 9, the required monthly trust reconciliation, client trust listing, and comparison must be completed by the 25th day of the following month. Firms should confirm the current requirements and ensure that the required review and supporting documentation are completed.
How long must Ontario law firms retain trust accounting records?
The LSO specifies a ten-year retention period for certain trust account records and a six-year period for certain general account records. The precise requirements should be checked against the applicable rules and the specific record category.
What is Form 9A used for?
Form 9A is associated with electronic trust transfer requisitions. Firms must follow the applicable By-Law 9 requirements for requisitions, authorizations, transfer records, and bank confirmations.
What are common LSO spot audit deficiencies?
Common issues identified in LSO spot audit guidance include financial records that are not current, incomplete transaction particulars, late monthly trust comparisons, unresolved reconciling items, electronic trust transfer deficiencies, inactive client trust balances, incomplete client identification, and missing source-of-funds documentation.
What should a law firm do if a trust reconciliation does not balance?
Investigate the discrepancy promptly, identify and document the cause, and take appropriate corrective action. Do not leave unexplained items unresolved or assume that a difference will correct itself in a later period.
Can legal practice management software guarantee LSO compliance?
No. Software can support record-keeping, workflow consistency, reminders, and review processes, but compliance depends on the firm's actual practices, the system's capabilities and configuration, and the applicable regulatory requirements.